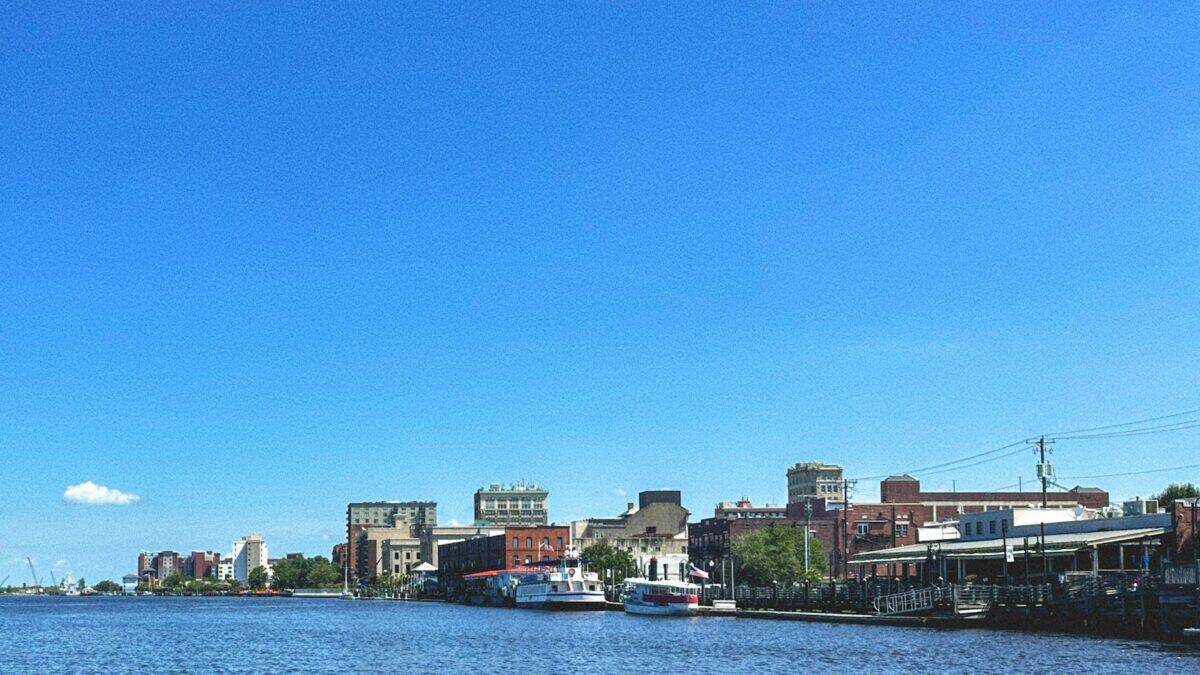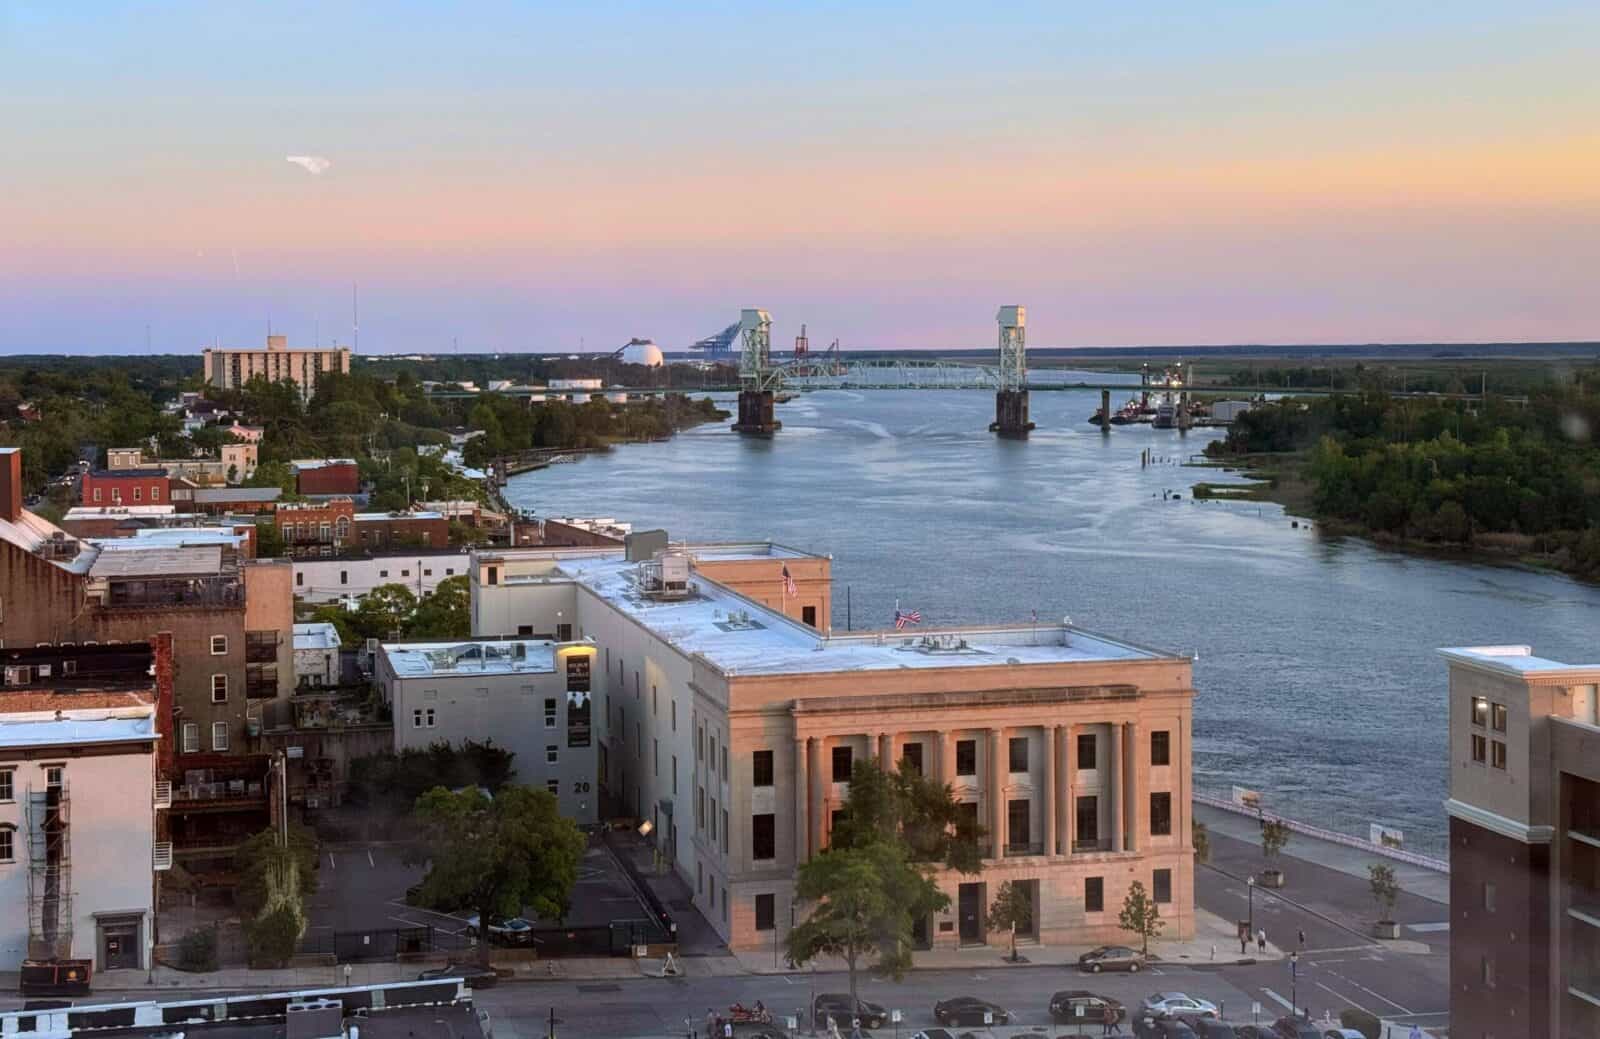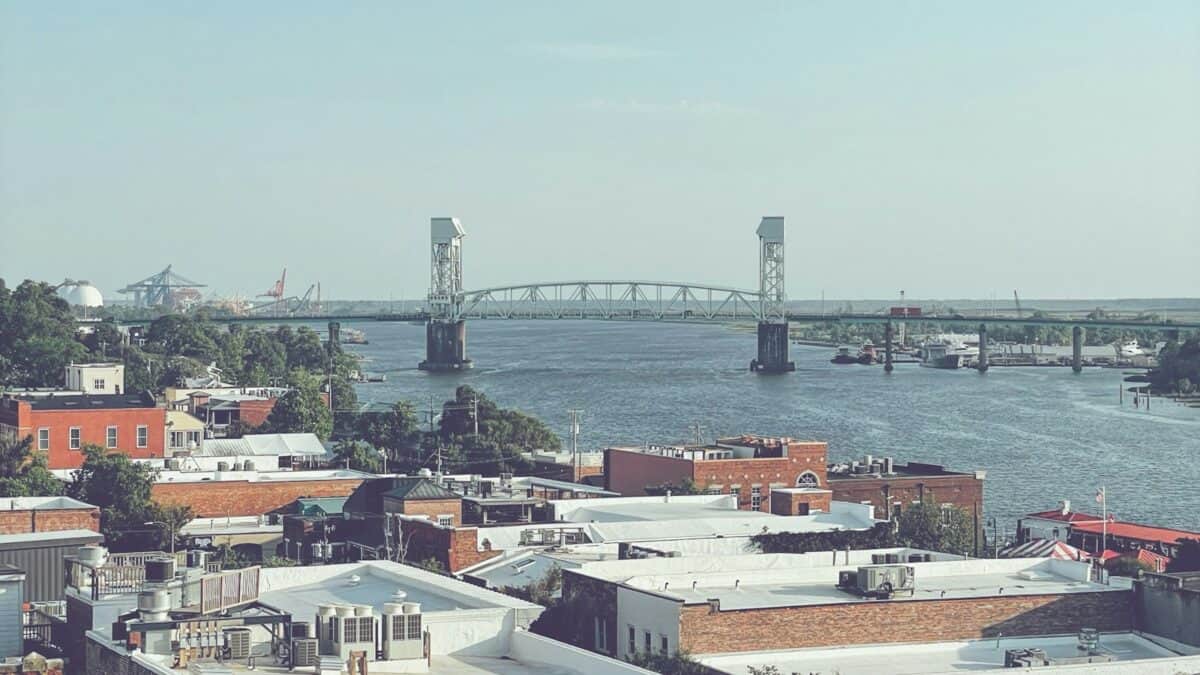
Becoming a first-time homebuyer in Wilmington, NC is exciting — and a little overwhelming. Between the Cape Fear River, the beaches, the military community, and a market that moves fast, there are a handful of local realities that catch new first-time homebuyers in Wilmington off guard. Here’s the honest, no-jargon rundown I give my own clients so you can shop with confidence and no surprises at the closing table.
Table of Contents
1. Get pre-approved before you fall for a house
Pre-qualified and pre-approved are not the same thing — and the difference matters. A pre-qualification is a rough estimate. A pre-approval means a lender has actually reviewed your income, credit, and assets and committed to a loan amount in writing. In a competitive Wilmington neighborhood, sellers often won’t even consider an offer without one, and it tells you your true budget before you emotionally attach to a home that’s out of reach. Start here so you’re shopping with a real number in hand. I break the two apart, step by step, in my guide to pre-approved vs. pre-qualified in Wilmington.
Moving to Wilmington?
Grab my free Moving to Wilmington Buyer Guide — neighborhoods, price ranges, and the local stuff nobody tells you before you fall for a house between the river and the sea.
2. Factor in the water — flood insurance can make or break your budget
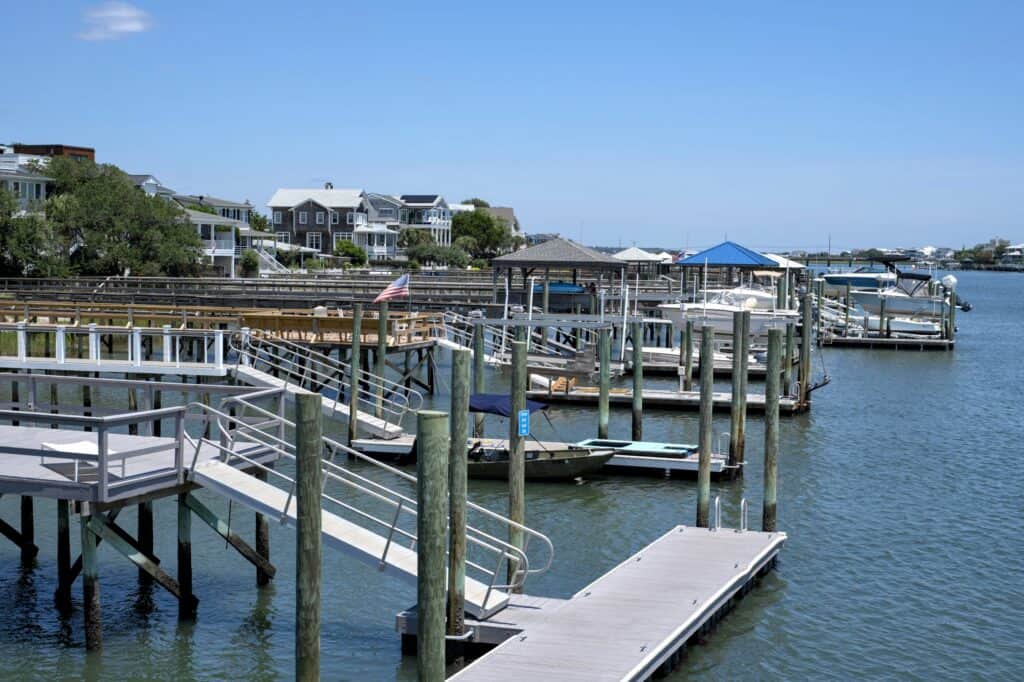
Living near the coast is the dream, but proximity to the water drives your flood-insurance costs, and two homes on the same street can sit in completely different flood zones. Before you fall in love with a house, look up its zone on the FEMA Flood Map Service Center and get an insurance quote — that monthly premium is part of your real payment, not an afterthought. Sometimes moving your search a few blocks inland saves you thousands a year. I walk through exactly what to check in insurance and flood zones in Wilmington.
3. Military-friendly loans are a real advantage here
Wilmington sits about an hour from Camp Lejeune, and the military community drives a big share of our market. If you’re a service member, veteran, or eligible surviving spouse, a VA loan can mean zero down payment and no private mortgage insurance — a powerful edge for a first-time homebuyer in Wilmington. Even if you’re not military, it helps to understand VA offers, because you’ll likely be competing against buyers who are using them. Ask your lender which loan programs — VA, FHA, USDA, or conventional — fit your situation best.
4. Plan for the property-tax surprise
New Hanover County tax rates are reasonable, but appraisals have been rising fast, and reassessments can bump your bill well above what the current owner pays. Two homes a mile apart can also carry very different tax bills depending on whether they sit inside Wilmington city limits. Don’t budget off the seller’s old tax number — ask what a reassessment could look like at your purchase price. I explain how it all fits together in county taxes and city limits explained.
5. Budget for closing costs from day one
North Carolina closing costs are moderate — typically about 2–3% of the purchase price — but on a $350,000 home that’s still roughly $7,000 to $10,500 you’ll need on top of your down payment. These cover things like lender fees, the appraisal, title work, and prepaid insurance and taxes. Ask your agent and lender for a line-by-line estimate early, and know that in some cases the seller can contribute toward these costs. Going in with a clear number means no scramble in the final week.
Frequently asked questions from first-time buyers
How much do I need for a down payment in Wilmington?
It depends on your loan. VA and USDA loans can require zero down for eligible buyers, FHA loans start around 3.5%, and conventional loans can start near 3%. Your down payment is separate from closing costs, so plan for both.
What credit score do I need to buy my first home?
Many first-time buyers qualify with scores in the low-to-mid 600s, and some programs go lower. A higher score generally means a better interest rate, so it’s worth checking with a lender early — even if you think you’re not ready yet.
Should I consider a short sale or foreclosure?
They can be great deals, but they come with tradeoffs — longer timelines, as-is condition, and more paperwork. If you’re curious, read buying a short sale or foreclosure in North Carolina before you make an offer.
Ready to start?
Buying your first home should feel exciting, not scary — and you don’t have to figure it out alone. Text or call me, Tabi, at 910-983-8963, or reach out through makingilmhome.com. Let’s find your home between the river and the sea.
Hear it from the people who do this for a living
Two conversations from my podcast worth your time: Joey Milam, a twenty-year mortgage advisor, on getting the seller to cover your closing costs, and Heath Altman of Alpha Mortgage on what your lender will ask for, and why.
Tabetha Klein is a licensed REALTOR® with Coldwell Banker Sea Coast Advantage. This article is for general educational purposes and is not lending, legal, tax, or financial advice. Loan programs, tax rates, and closing costs vary by situation and change over time — please consult a licensed mortgage lender, tax professional, or attorney about your specific circumstances. Each office is independently owned and operated. Equal Housing Opportunity.
Keep going on your first purchase
Ready for the next step? Start with my full guide to buying a home in Wilmington, NC, learn the difference between getting pre-approved and pre-qualified, dig into insurance and flood zones, understand county taxes and city limits, and see what buying a short sale or foreclosure really involves.