Beach Investment Property NC: Primary Home vs. Second Home vs. Investment
Beach investment property NC is on a lot of my buyers’ wish lists. Dreaming of a place near the water at Wrightsville, Carolina Beach, or Kure Beach? Wonderful — me too, honestly. But here’s something a lot of buyers don’t realize until we start: how you plan to use a beach property changes almost everything about how you buy it. The same house can be a primary home, a second home, or an investment — and each path has different financing, insurance, and tax implications.
Let’s untangle the three so you know which conversation to have with your lender and CPA. (And yes — I’m a REALTOR®, not a lender, CPA, or insurance agent, so treat this as orientation, not advice. The specifics belong with those professionals.)
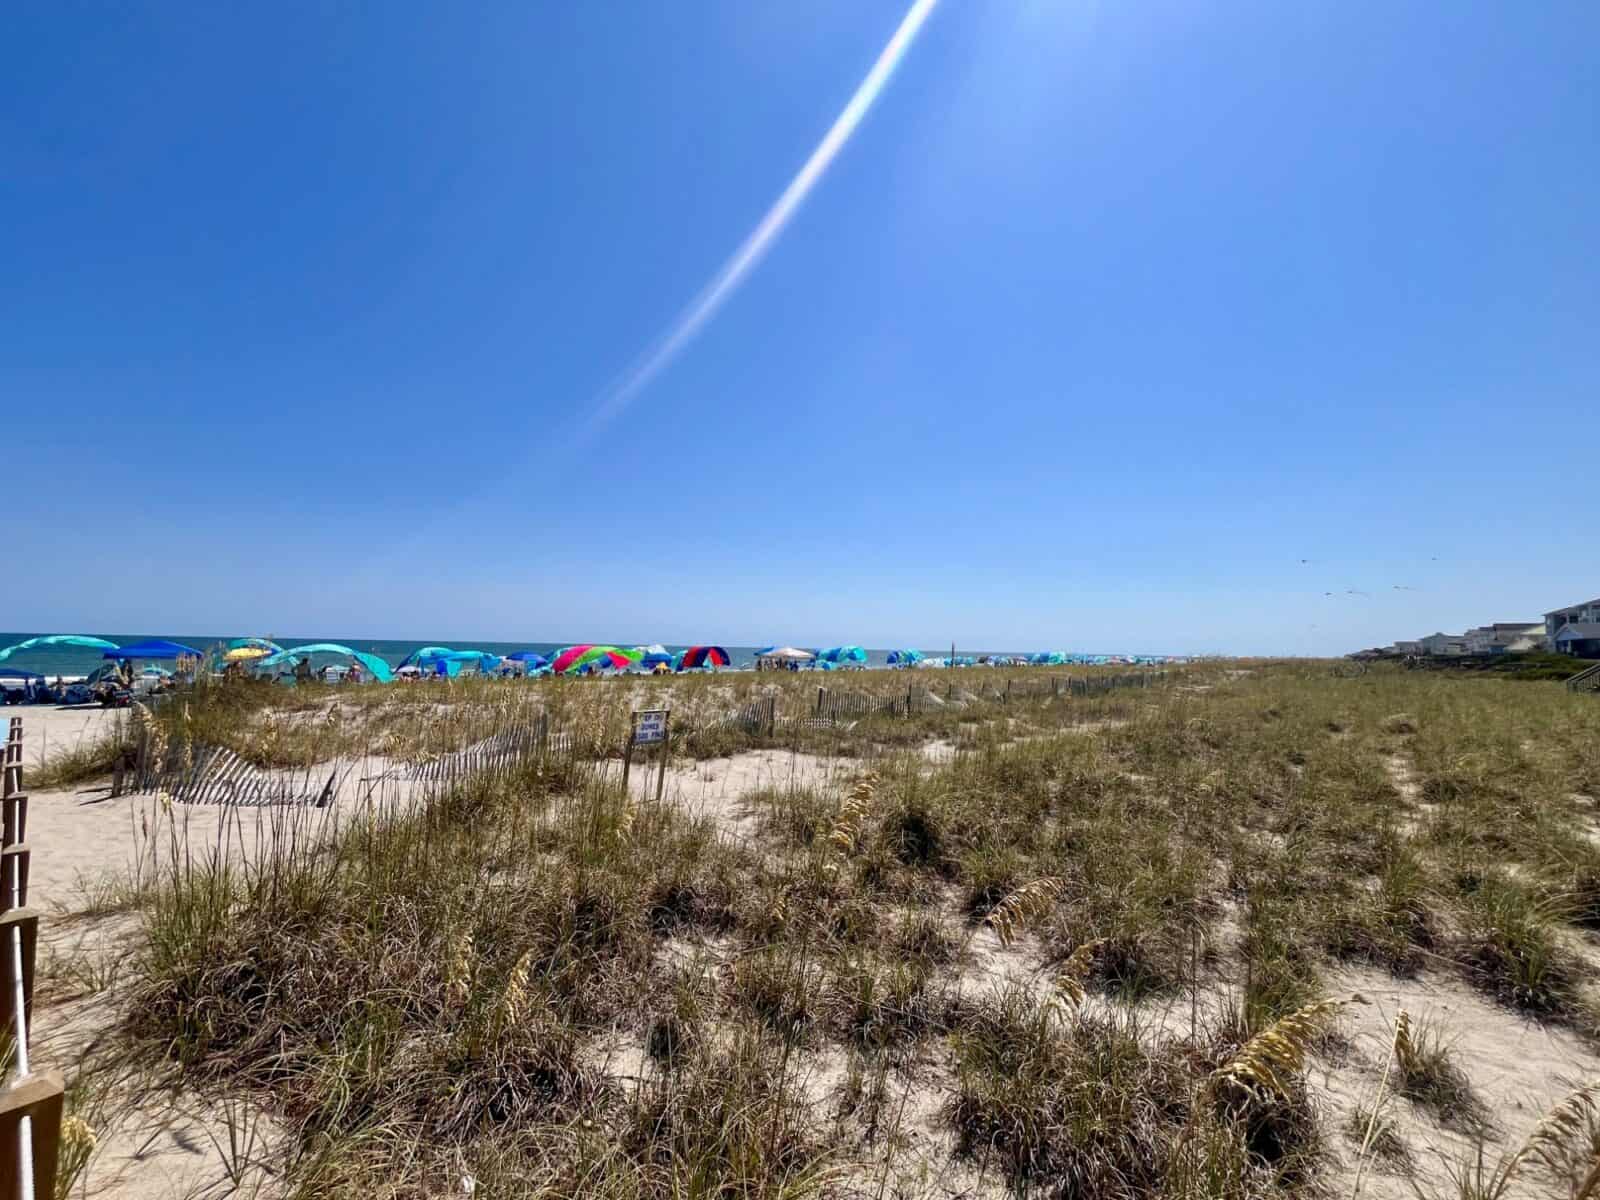
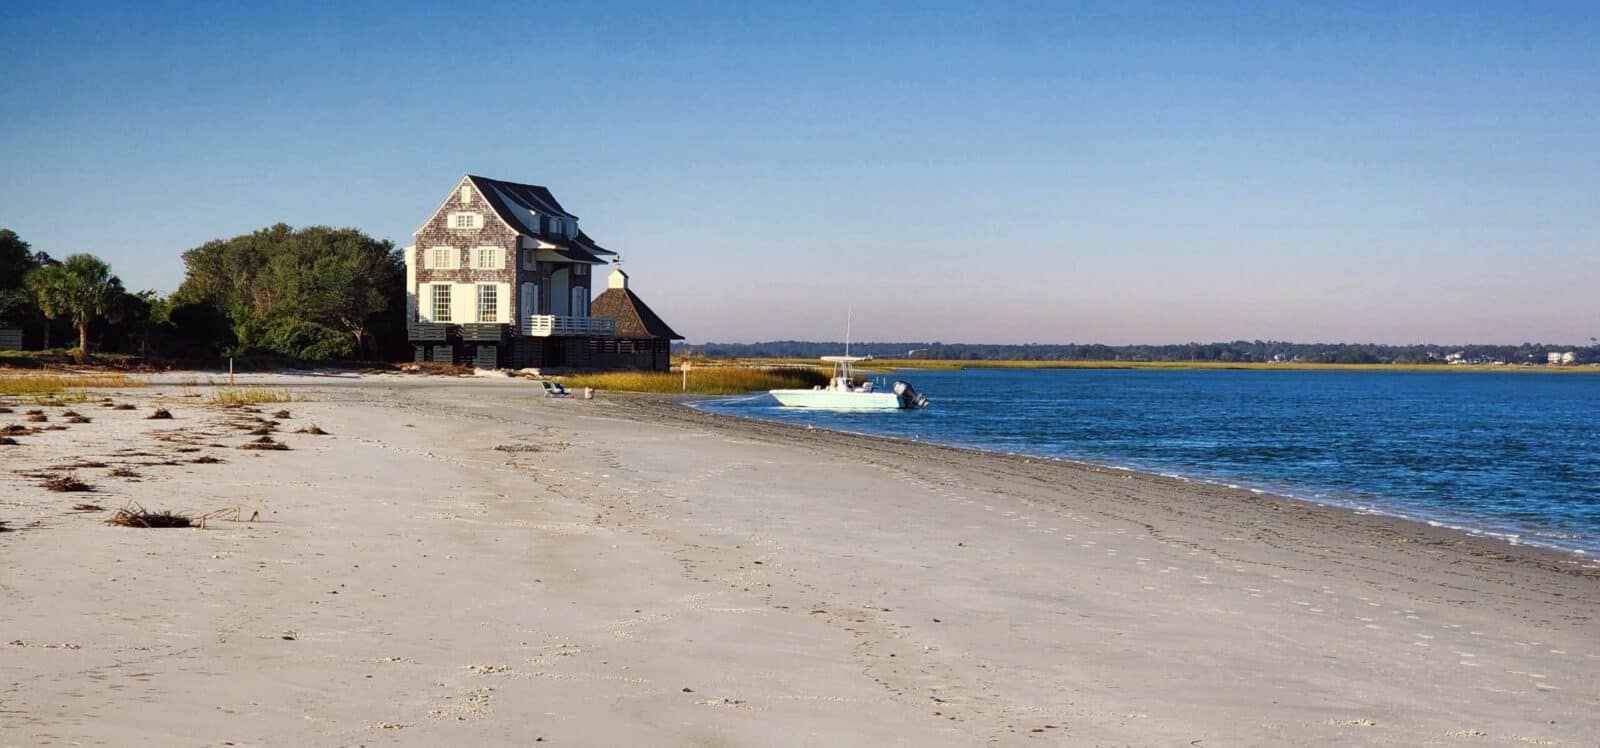
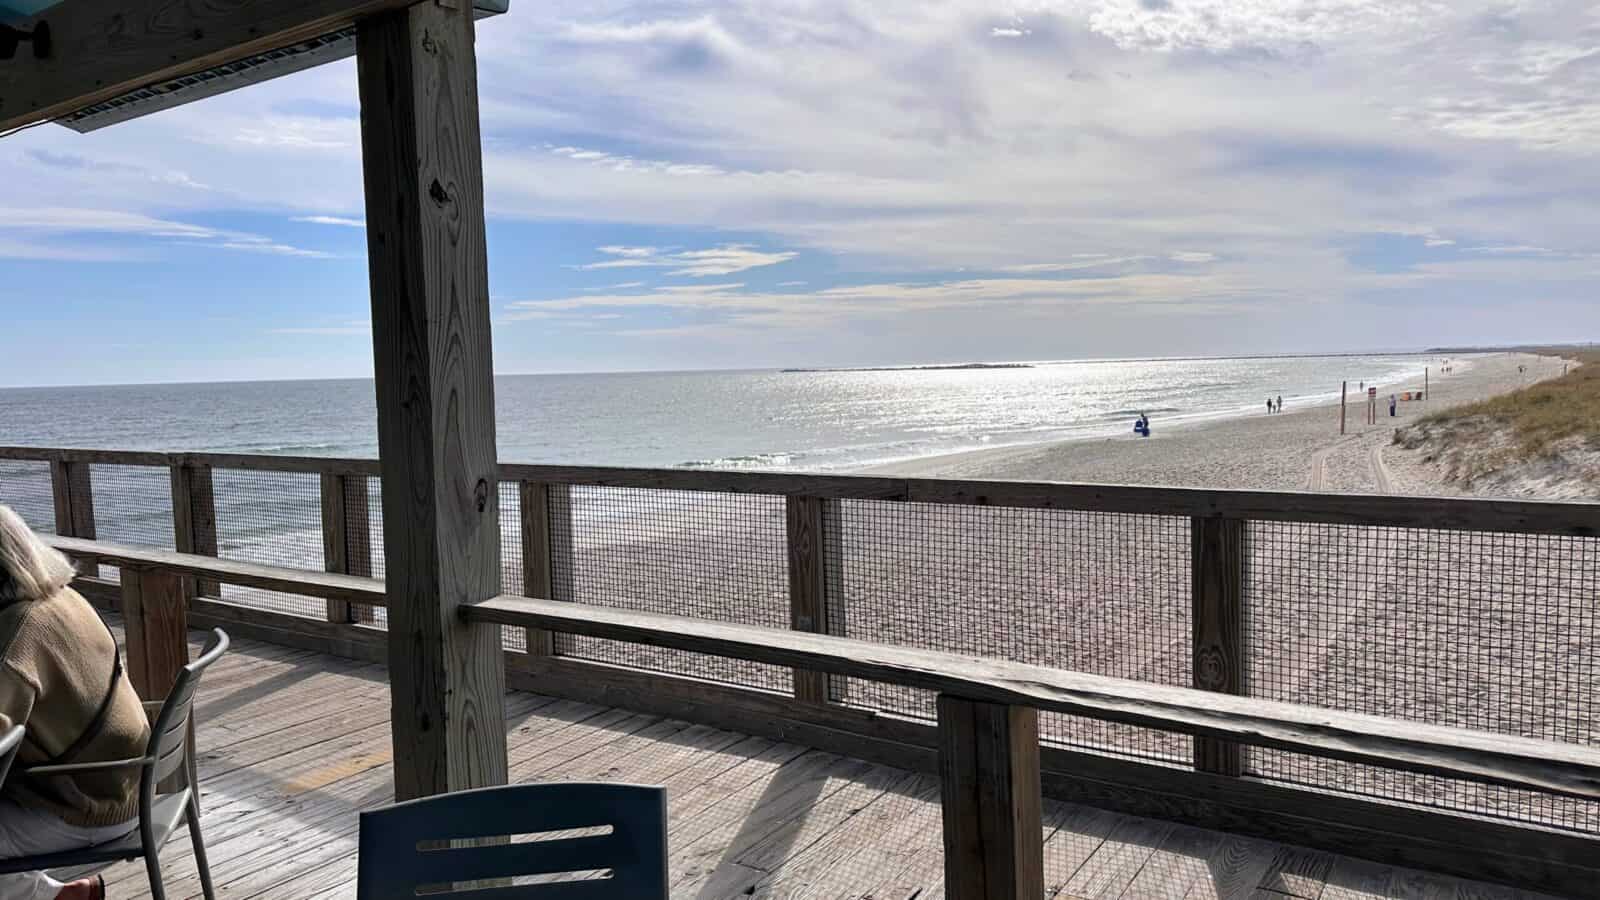
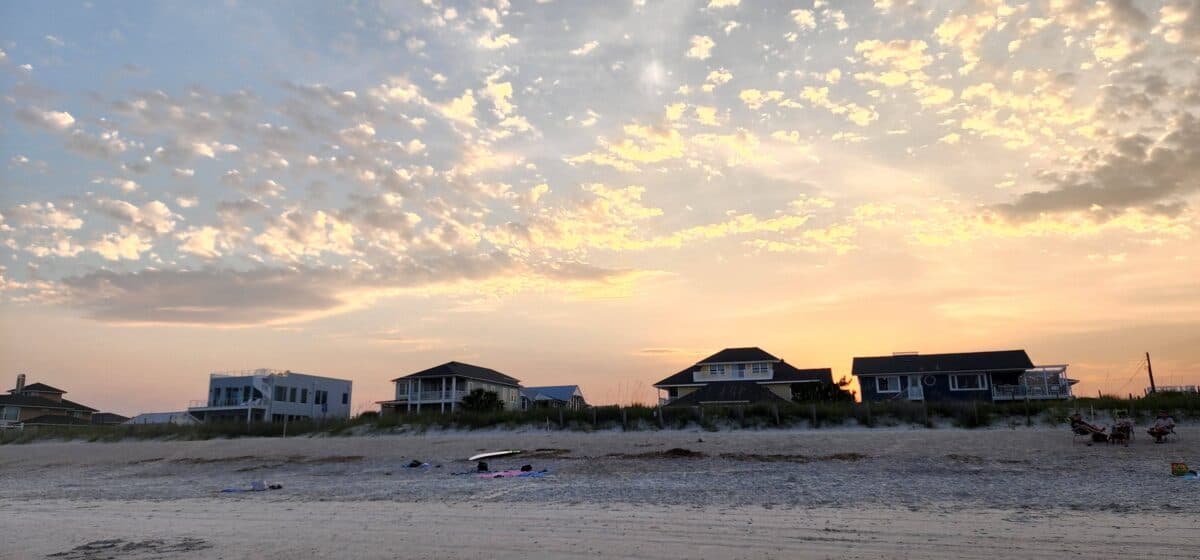
Wide sandy beach on a bluebird North Carolina day — the lifestyle a beach purchase is really buying.
Moving to Wilmington?
Grab my free Moving to Wilmington Buyer Guide — neighborhoods, price ranges, and the local stuff nobody tells you before you fall for a house between the river and the sea.
1. Primary residence
This is a home you’ll live in most of the year — your actual address.
- Financing: primary homes usually get the most favorable loan terms and down-payment options, because lenders see them as lower risk.
- Insurance: standard owner-occupied coverage (plus the coastal wind/flood considerations we talk about in my insurance & flood zones post).
- Taxes: as your main home, it may qualify for certain owner-occupant benefits — your CPA can walk you through what applies in NC.
A fit when: the home will be your full-time address on the coast.
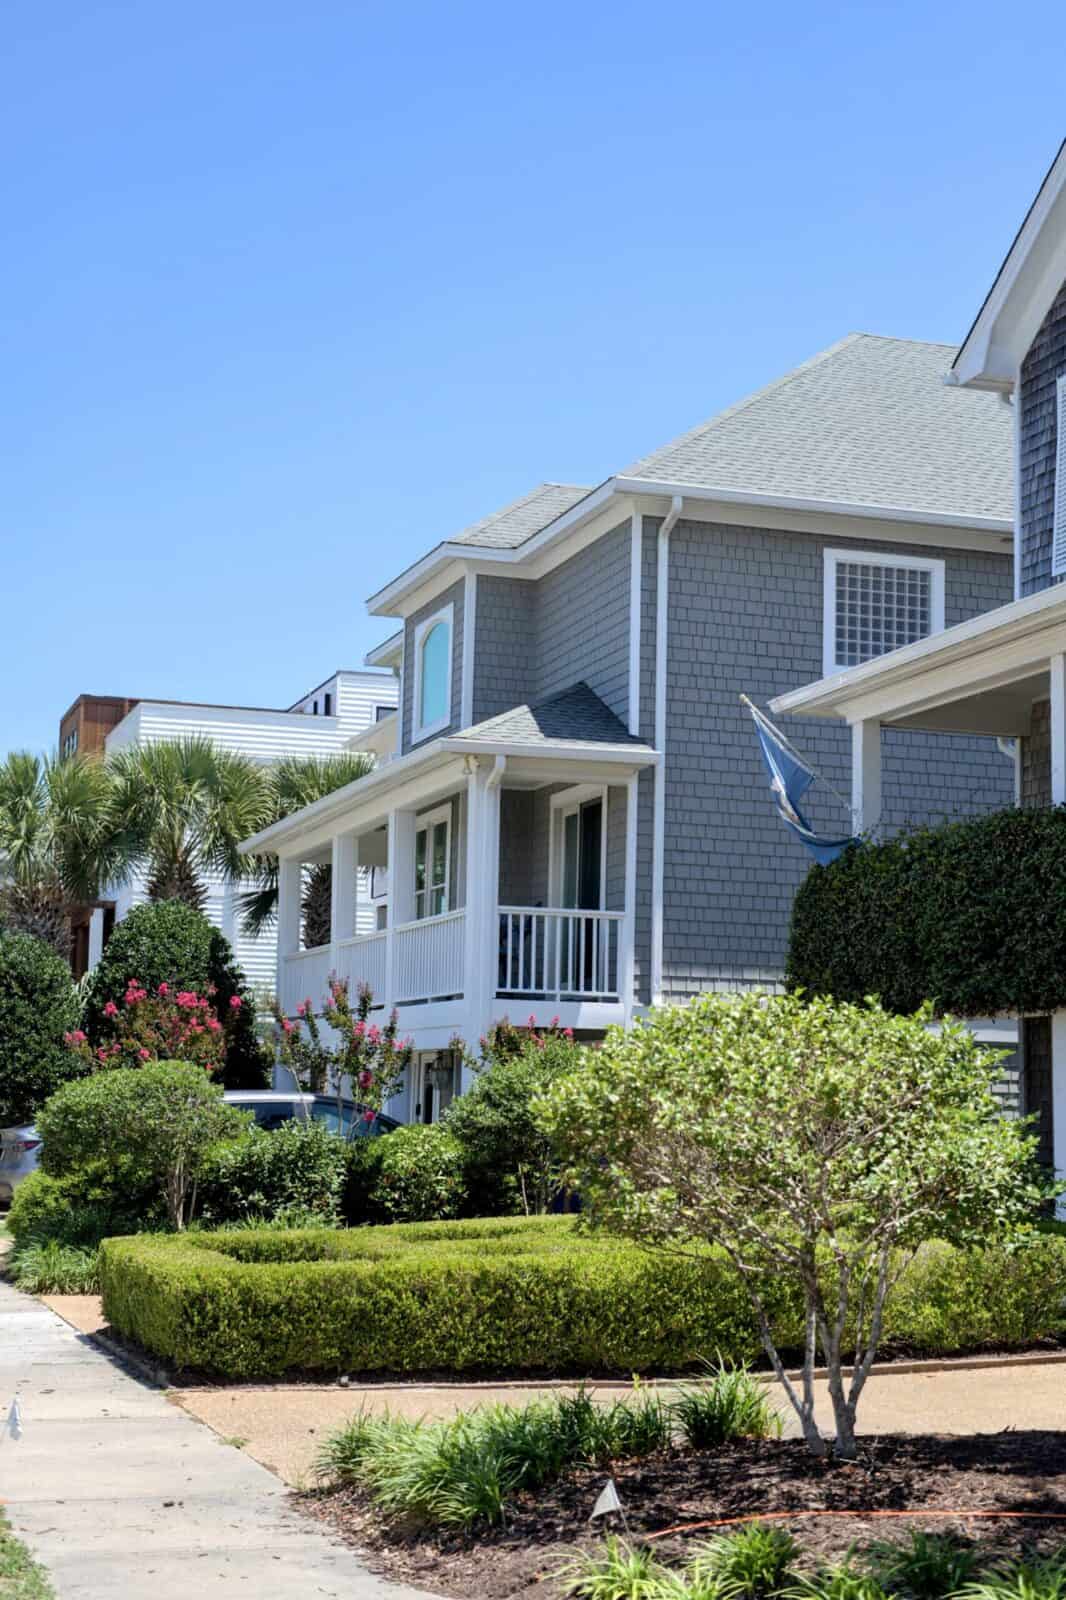
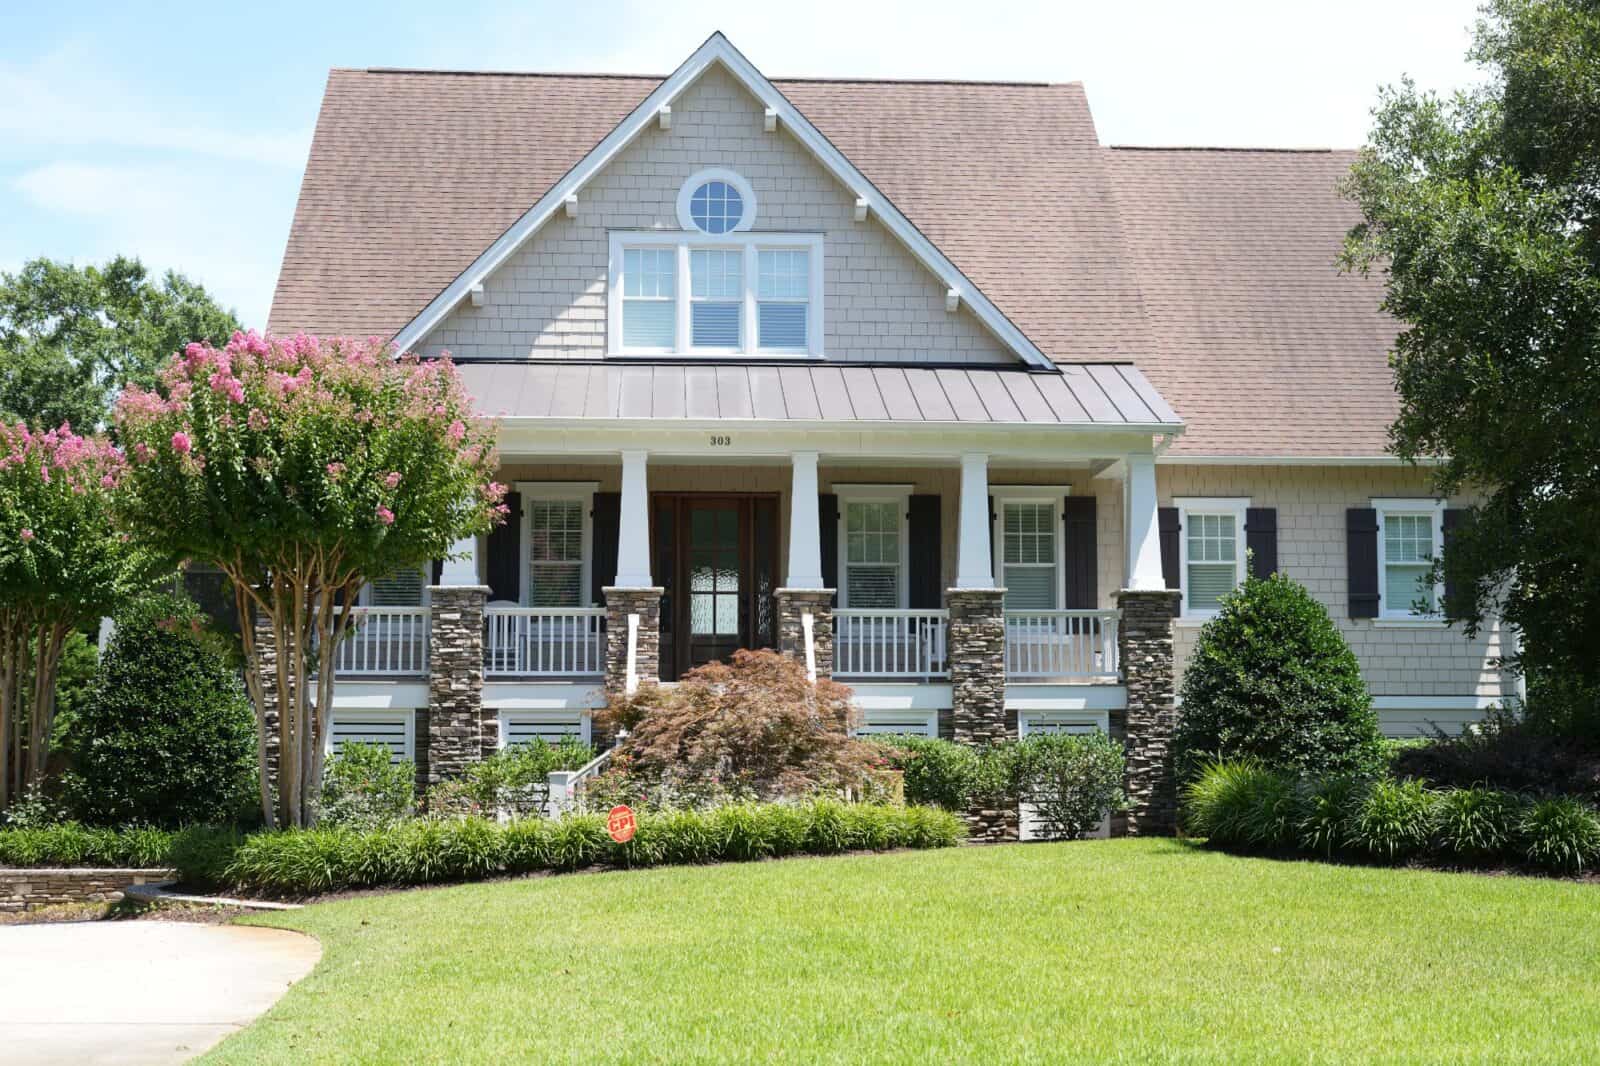
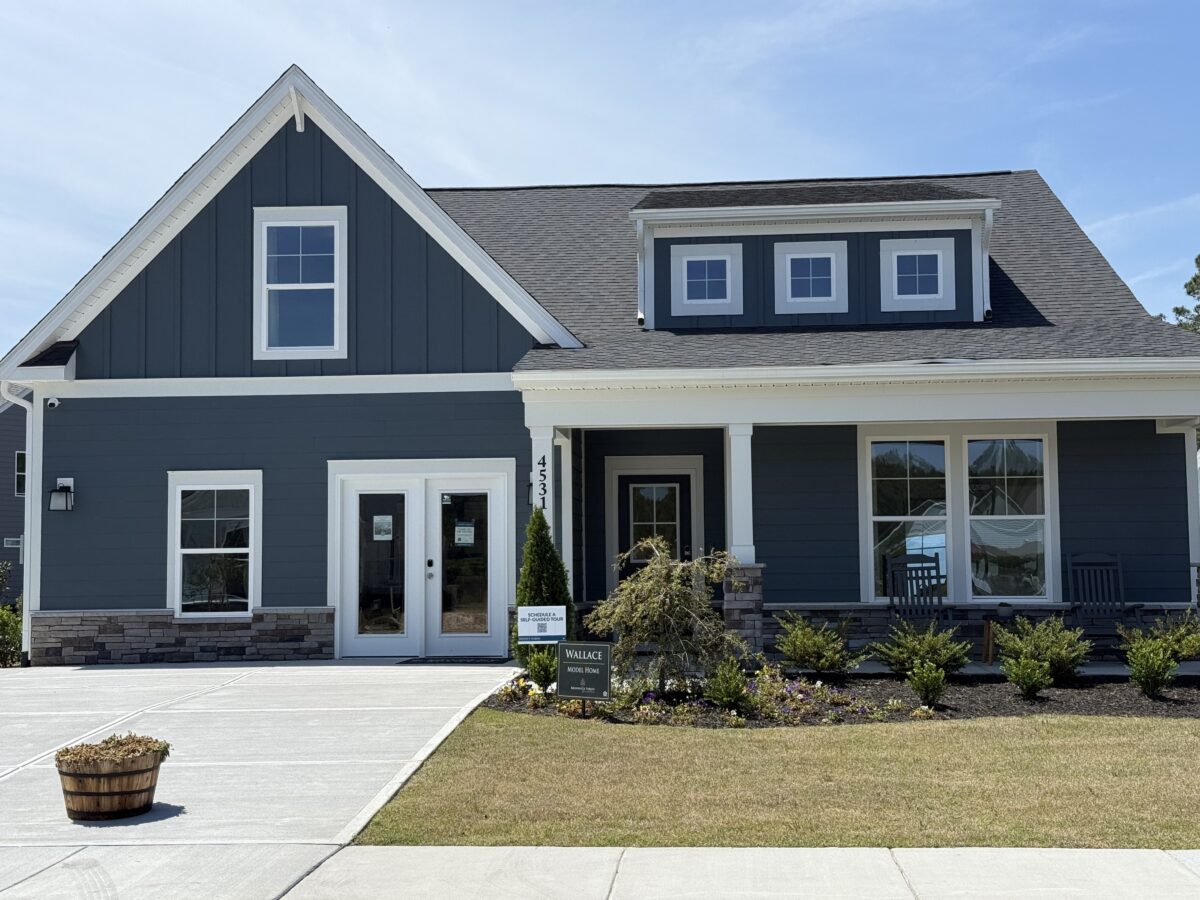
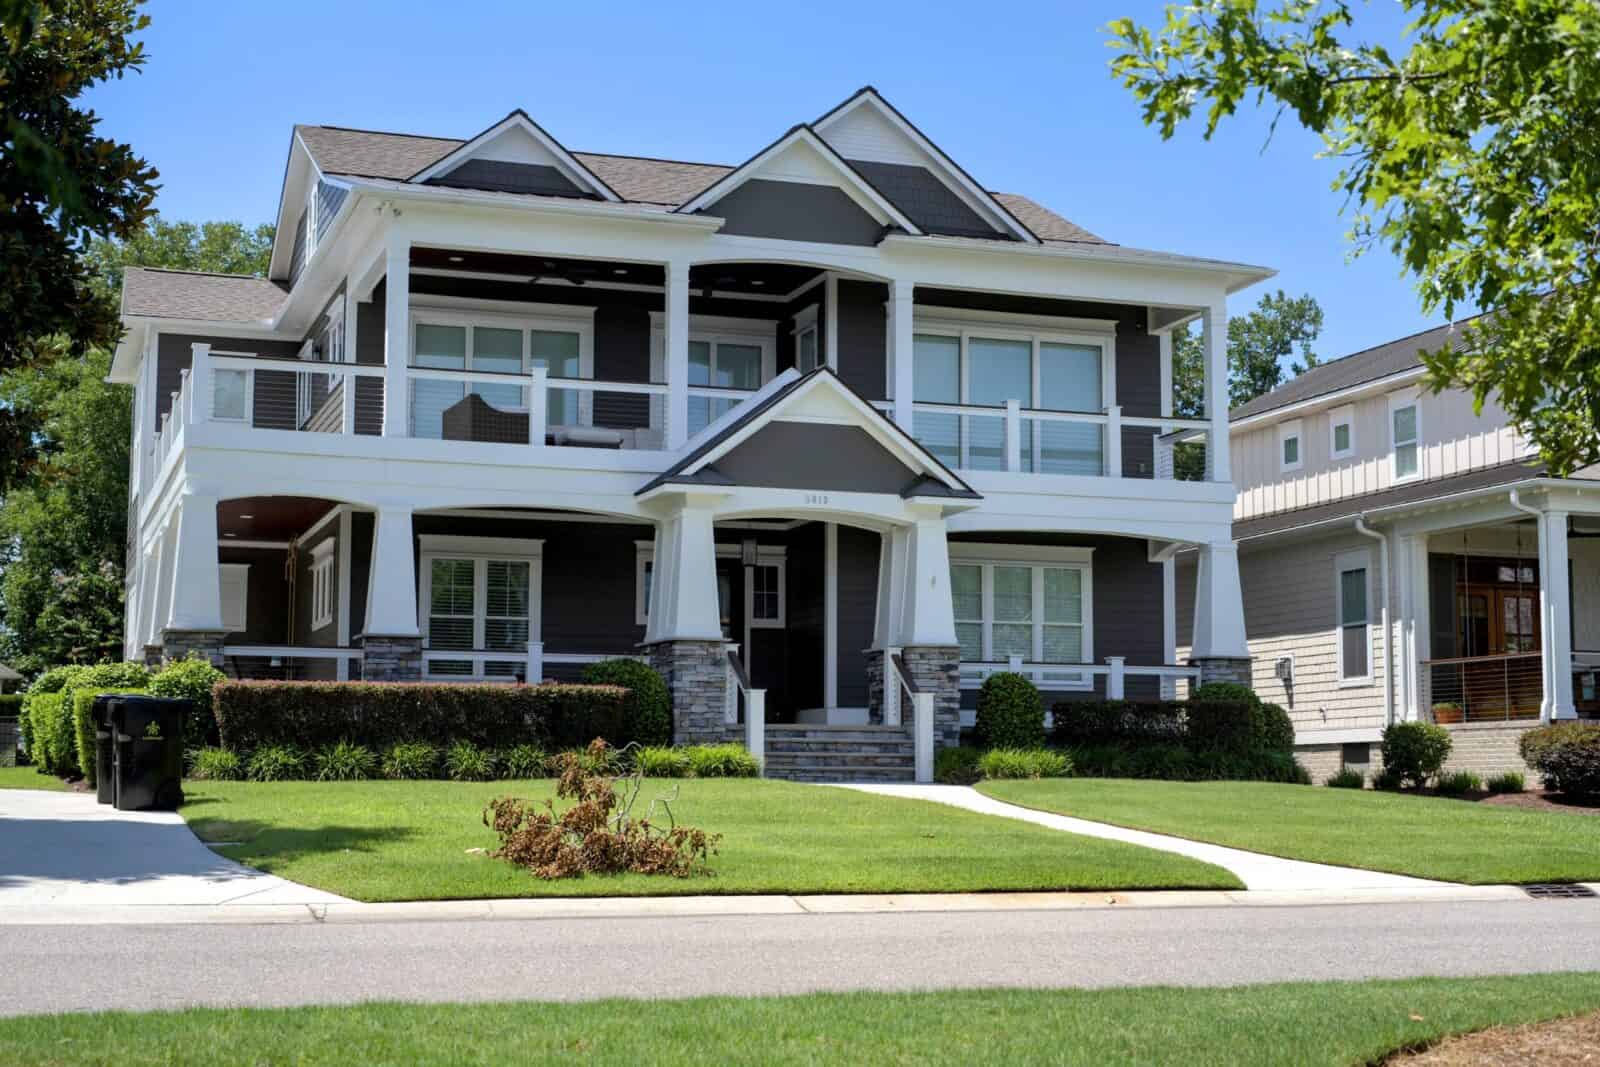
The kind of home you’d actually live in every day — not just visit on weekends.
2. Second home / vacation home
A place you’ll use personally — weekends, summers, holidays — but that isn’t your primary address.
- Financing: second-home loans are common, but typically expect a larger down payment and slightly different terms than a primary. Lenders usually require that you use it and that it’s not a full-time rental.
- Insurance: may cost more than a primary, especially a coastal property that sits empty part of the year.
- Taxes: the rules around personal use vs. any rental use get nuanced fast — definitely a CPA conversation. The IRS rules on personal use vs. rental use are here.
A fit when: you want your own escape for personal use, without running it as a business.
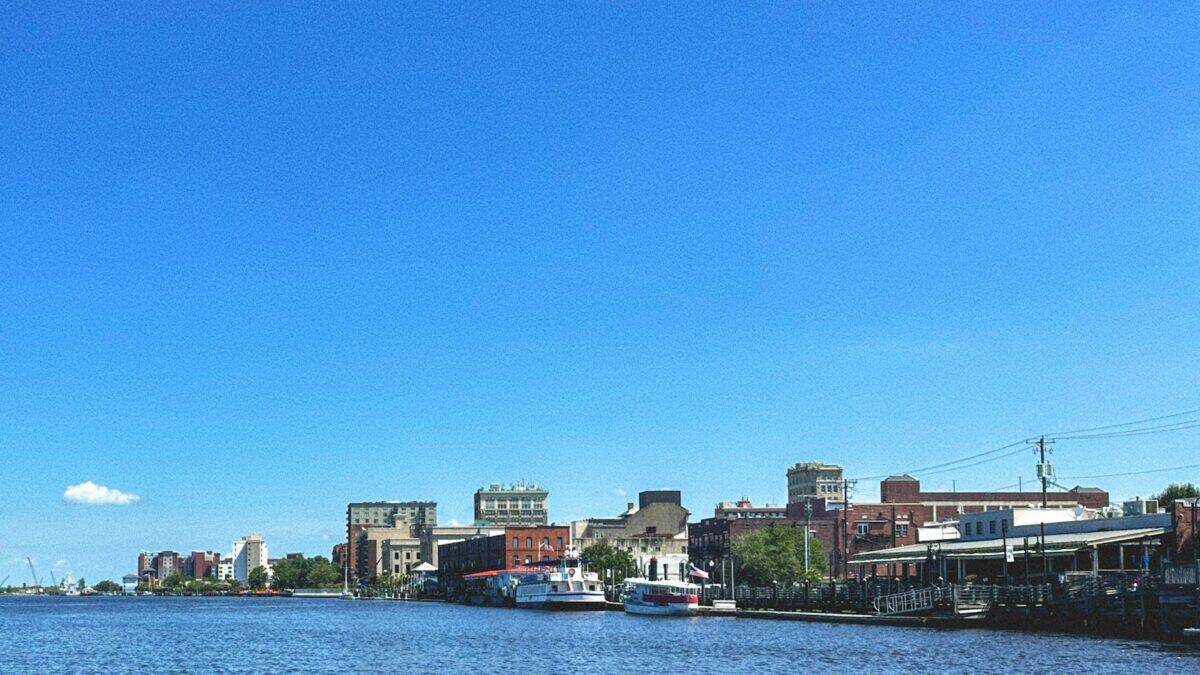
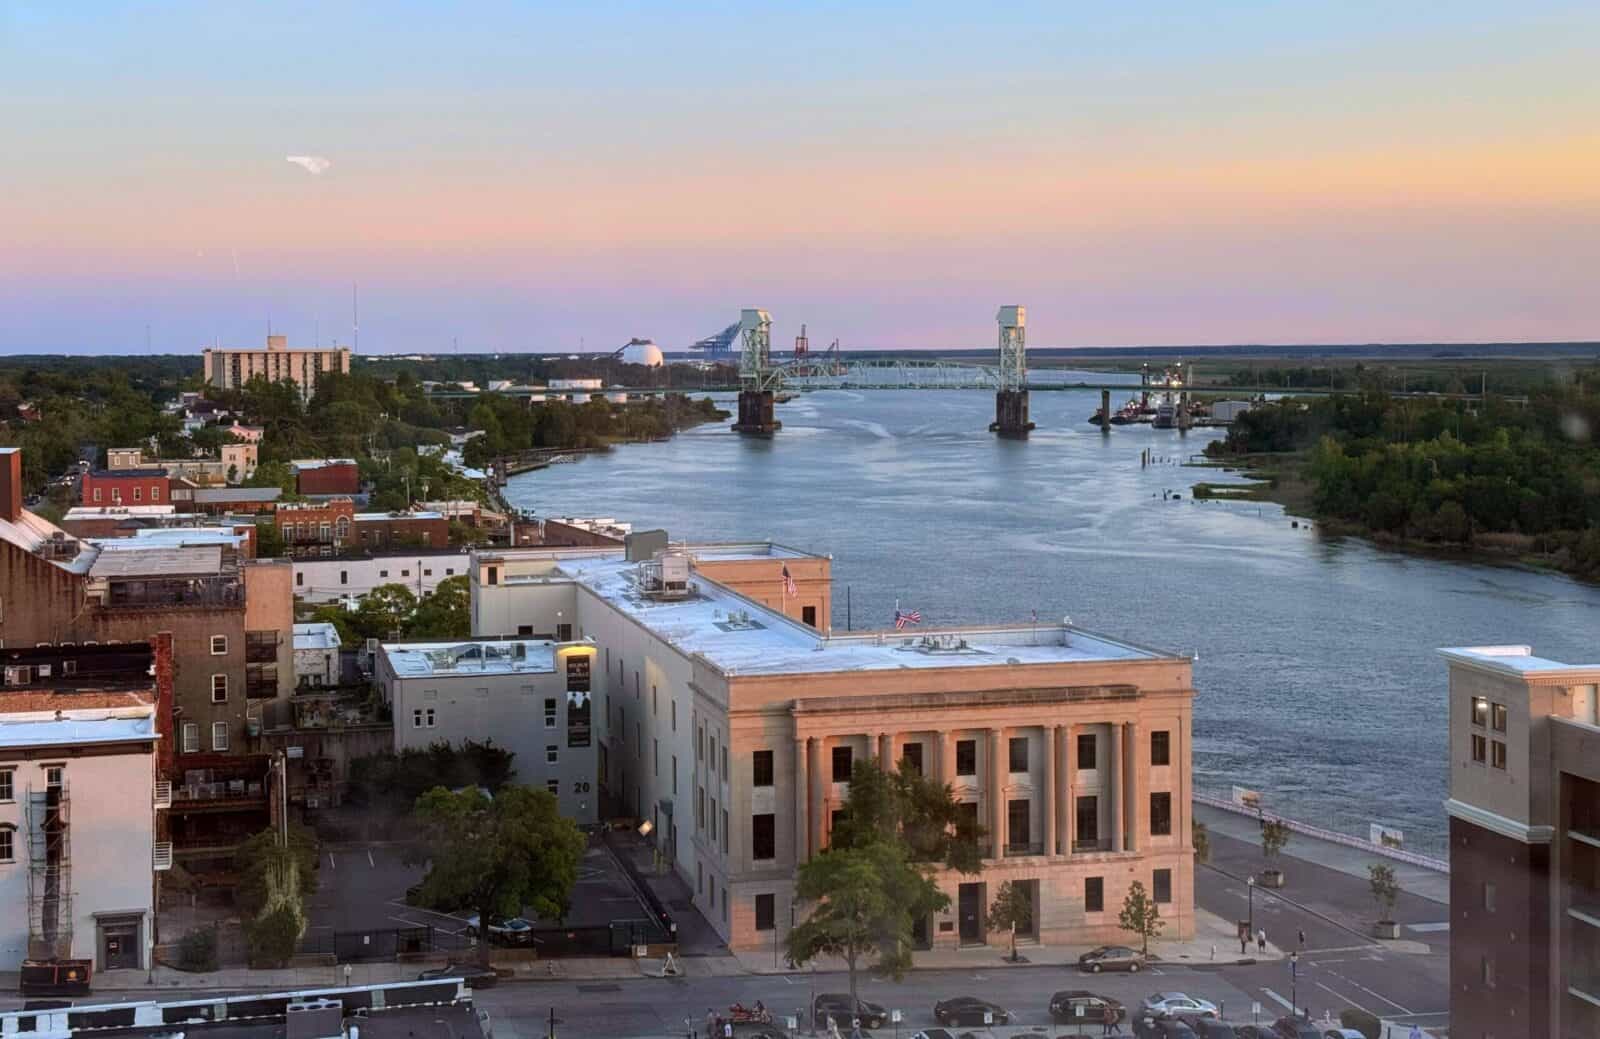
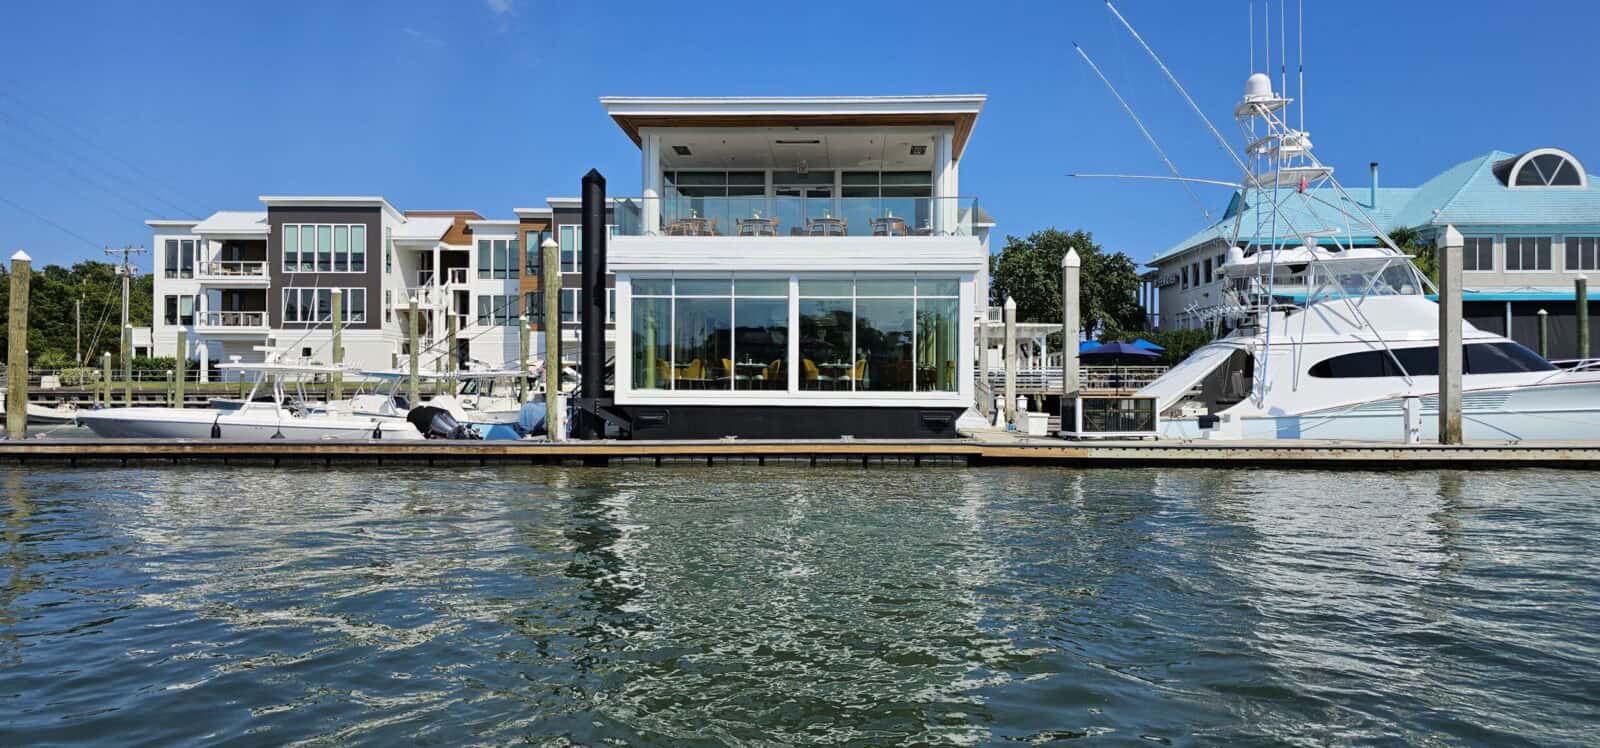
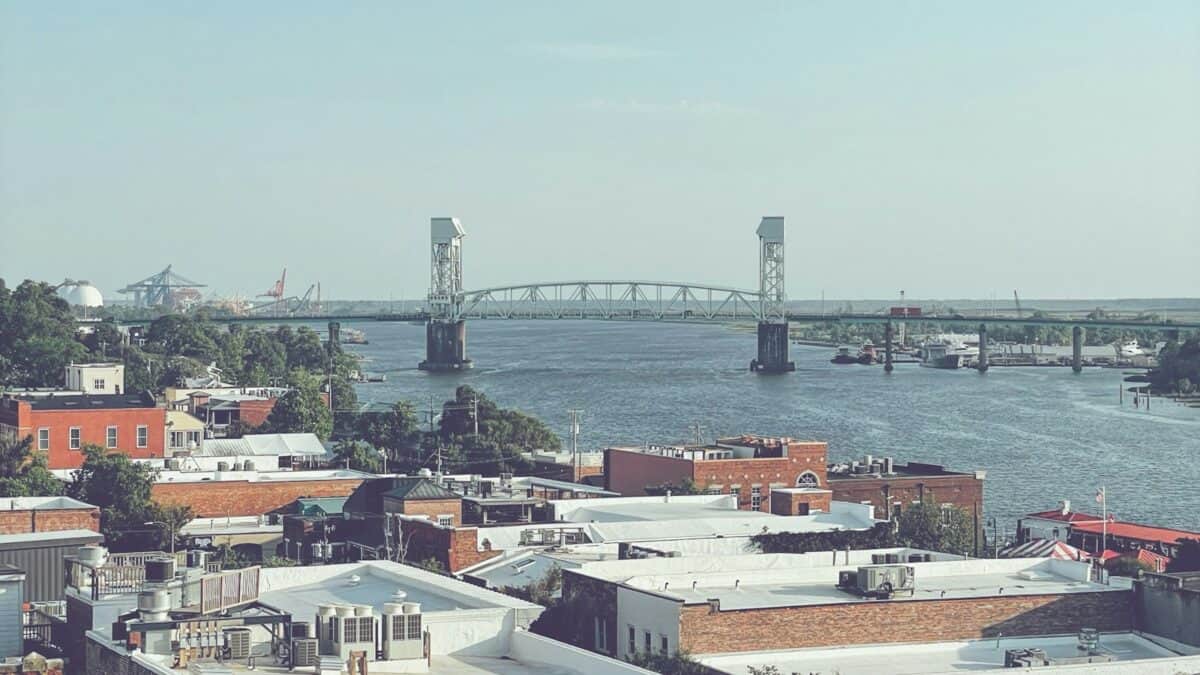
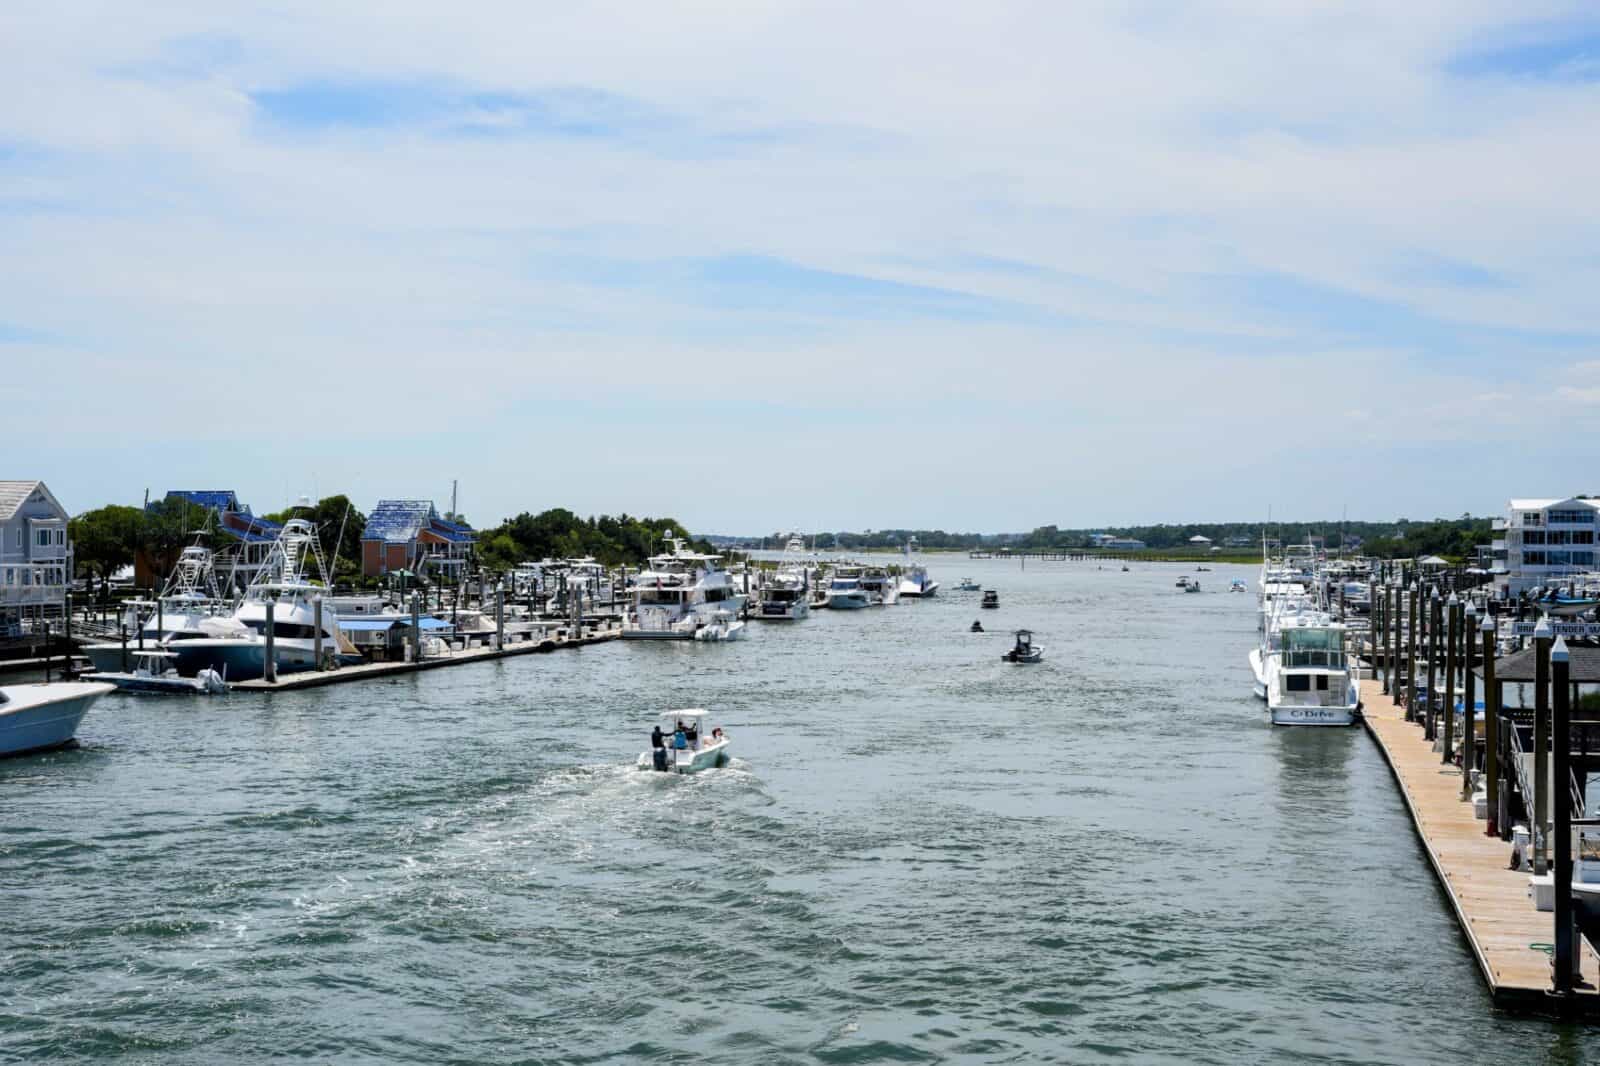
Working by the marina — the kind of everyday use worth thinking through before you pick a loan type.
3. Investment / rental: buying a beach investment property NC
A property you buy primarily to rent out — whether long-term or as a short-term vacation rental.
- Financing: investment loans generally carry the highest down-payment and rate requirements of the three, because they’re considered the highest risk.
- Insurance: landlord or short-term-rental policies differ from owner-occupied coverage.
- Taxes: rental income, expenses, and depreciation all come into play — this is very much CPA territory.
- Local rules matter a lot: short-term rental regulations vary by town and even by neighborhood or HOA. Wrightsville Beach, Carolina Beach, and Kure Beach each have their own rules, and some communities restrict rentals entirely. Always verify what’s allowed for a specific property before you count on rental income.
A fit when: the property’s main purpose is rental use, you’ve confirmed the local rental rules, and you’ve run realistic numbers with your lender and CPA. Investors hunting for a bargain should also understand short sales vs. foreclosures in NC before chasing a distressed listing.
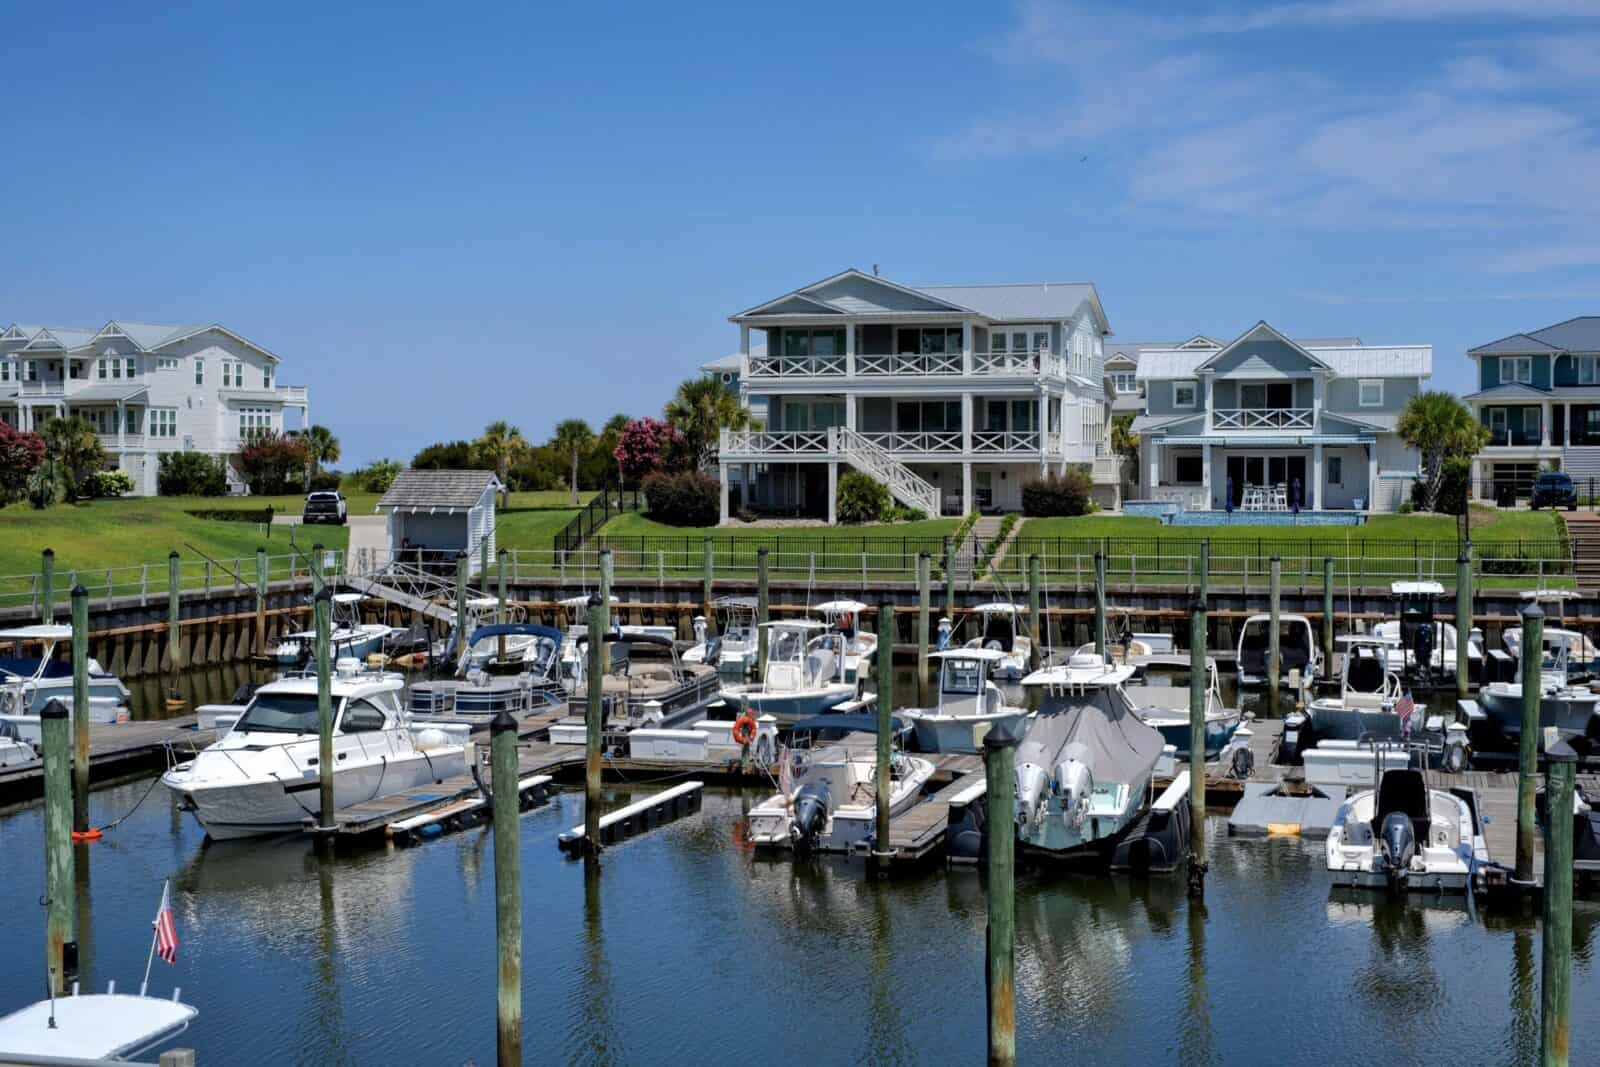
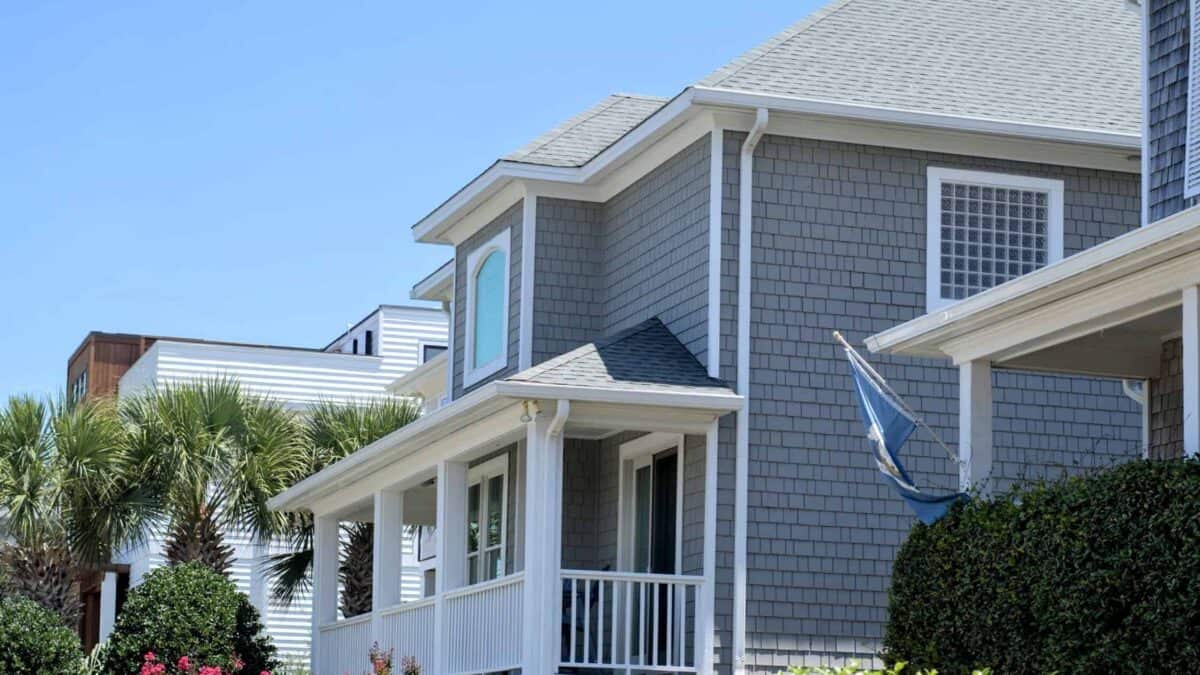
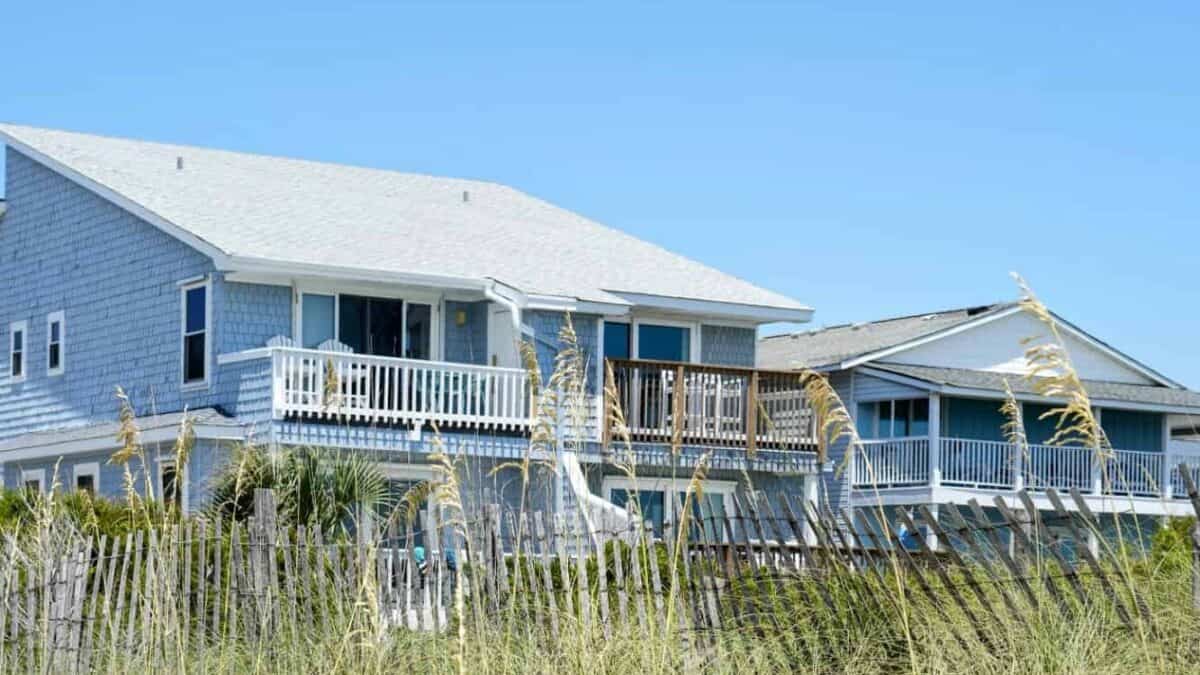
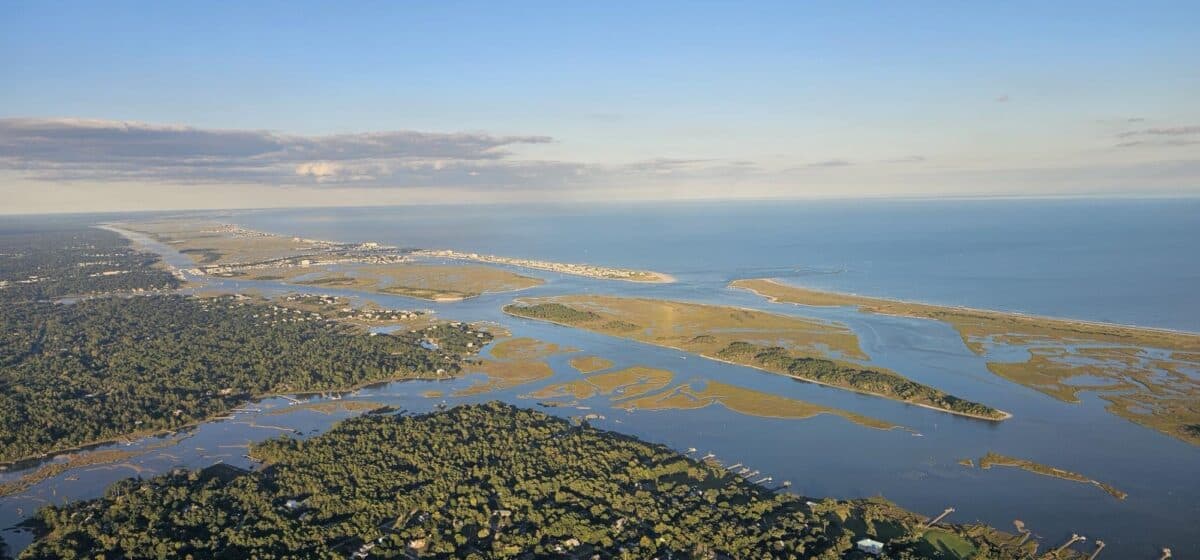
Waterfront homes overlooking a Wrightsville Beach marina — if you’re considering rental use, always verify local STR rules before you buy.
Why sorting this out first saves you headaches
Every one of these paths starts with the same house but a different game plan. If you tell your lender “second home” but plan to rent it out full-time, or you assume a beach cottage can be a short-term rental when the town says otherwise, you can end up with the wrong loan, the wrong insurance, or a plan that doesn’t pencil out. Getting clear on the use up front lets your whole team — lender, CPA, insurance agent, and me — point you at the right property from day one.
Frequently asked questions
What is the difference between a second home and an investment property in NC?
A second home is a place you use personally, such as weekends, summers and holidays, that isn’t your primary address; lenders usually require that you use it and that it isn’t a full-time rental. An investment property is one you buy primarily to rent out, whether long-term or as a short-term vacation rental.
Does a beach investment property in NC need a bigger down payment?
Generally, yes. Investment loans usually carry the highest down-payment and rate requirements of the three types, because lenders consider them the highest risk. Second-home loans typically expect a larger down payment than a primary residence.
Can I use a beach house in Wrightsville Beach, Carolina Beach, or Kure Beach as a short-term rental?
It depends on the property. Short-term rental rules vary by town and even by neighborhood or HOA. Wrightsville Beach, Carolina Beach, and Kure Beach each have their own rules, and some communities restrict rentals entirely. Verify what’s allowed for a specific property before you count on rental income.
What insurance does a beach rental property in NC need?
Landlord or short-term-rental policies differ from standard owner-occupied coverage. A second home may cost more to insure than a primary, especially a coastal property that sits empty part of the year. Talk with a licensed insurance agent about the specific property.
Why does it matter how I plan to use a beach property in NC?
The same house can be a primary home, a second home, or an investment, and each path has different financing, insurance, and tax implications. If you tell your lender “second home” but plan to rent it full-time, or assume a cottage can be a short-term rental when the town says otherwise, you can end up with the wrong loan or the wrong insurance.
Let’s figure out your beach plan
Tell me how you picture using the place, and I’ll help you shape a search around it — and connect you with a lender, CPA, and insurance agent so the numbers are real before you fall in love with a view.
Text or call me, Tabi, at 910-983-8963, or reach out through www.makingilmhome.com. Let’s find your spot between the river and the sea.
Hear it from the people who do this for a living
Two from my podcast: Madison Williams, a coastal insurance specialist, on what coverage actually costs near the water, and Mike Breitfeller, CFP®, on how a second property fits into a longer financial plan.
Tabetha Klein is a licensed REALTOR® with Coldwell Banker Sea Coast Advantage. This article is for general educational purposes only and is not lending, tax, insurance, or legal advice. Loan terms, tax treatment, insurance, and short-term-rental rules vary by property, lender, and jurisdiction and change over time — consult the appropriate licensed professionals and verify local regulations for any specific property. Each office is independently owned and operated. Equal Housing Opportunity.
Keep going before you buy at the beach
Coastal ownership has its own math. Read what to check on insurance and flood zones, compare Wrightsville and Carolina Beach, explore my Wrightsville Beach neighborhood guide, and start with my guide to buying a home in Wilmington.